Real Estate News April 25, 2026

How Much Does a Pool or Spa Add to Your Home’s Value?

How Much Does a Pool or Spa Add to Your Home’s Value?

For many homeowners in San Diego County, a backyard pool or spa isn’t just a luxury — it’s a lifestyle upgrade. But if you’re thinking about buying, selling, or refinancing, you might wonder: how much does a pool or spa actually add to a home’s value according to appraisers?
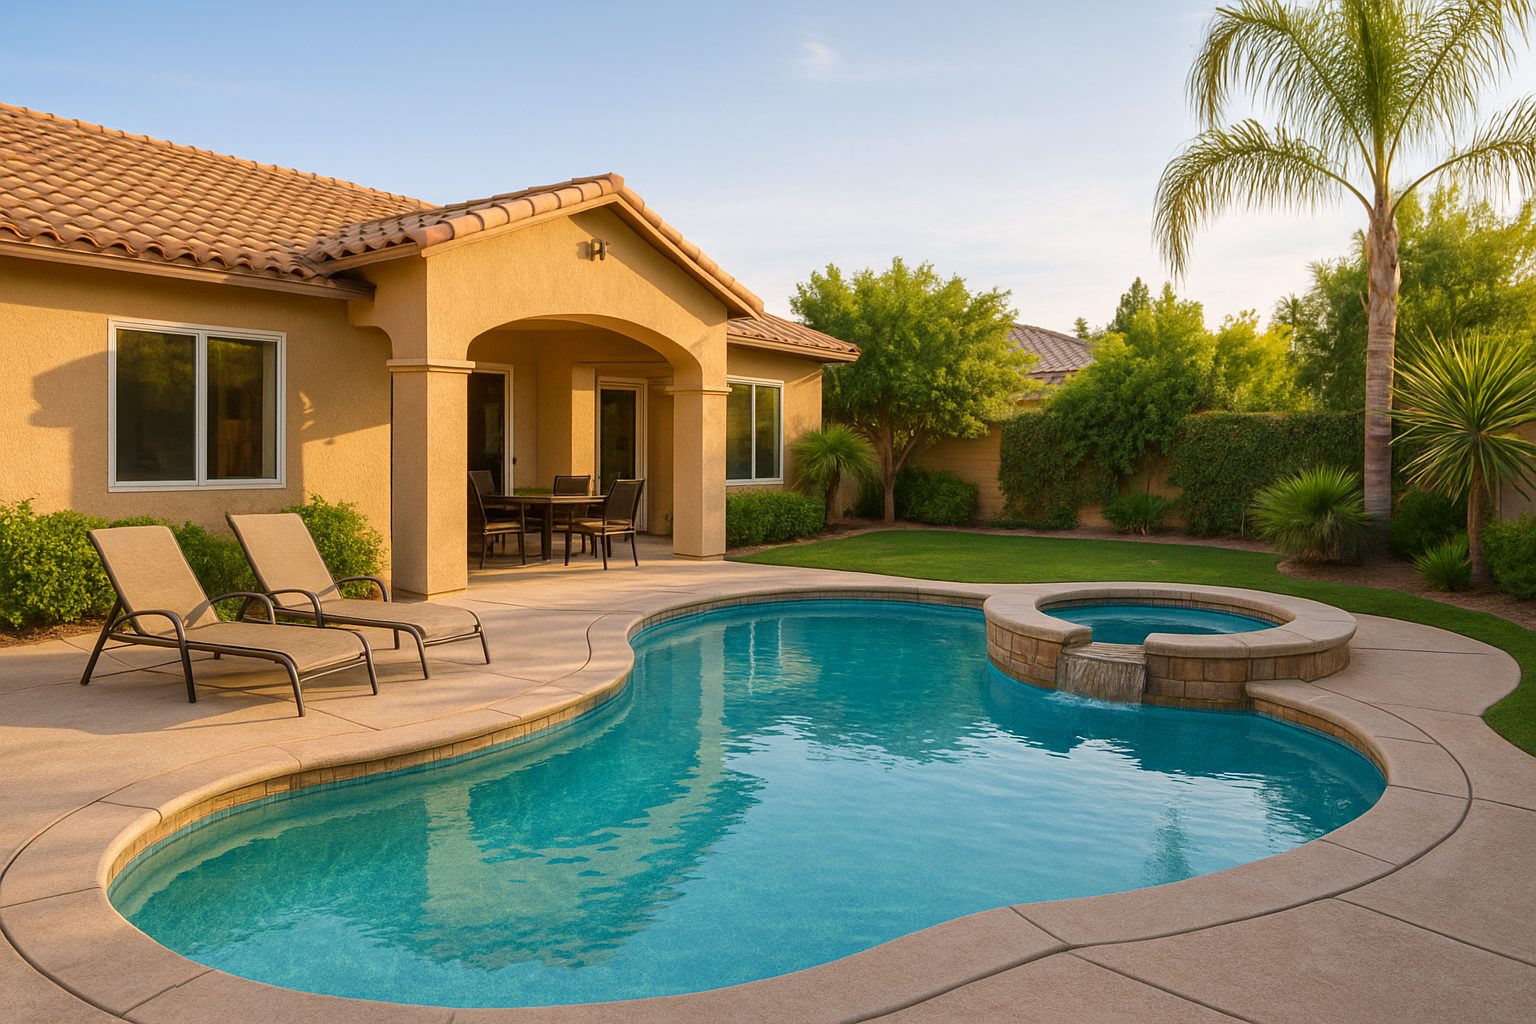
1. Pools and Spas Are Lifestyle Features, Not Always Cash in the Bank

While pools and spas are visually appealing and can make your home feel like a private resort, appraisers view them differently than structural features like kitchens or bathrooms. Pools are generally considered amenities, meaning they can enhance the appeal of a home but may not always provide a dollar-for-dollar return on investment.

2. Regional Differences Matter

In hotter climates like Southern California, pools are more desirable than in cooler areas. An appraiser in San Diego County recognizes that a well-maintained pool or spa can make a home more competitive in the market. However, the value added often depends on neighborhood norms. If most homes in your area have pools, it might add less value because it’s expected.

3. Typical Appraiser Adjustments

Appraisers typically make adjustments for pools and spas in the following ways:

  • Quality & Condition: A professionally installed, well-maintained pool adds more value than a DIY or poorly maintained one.
  • Size & Features: Standard pools add some value, but features like waterfalls, heating, or spa integration can increase adjustments.
  • Market Preference: If buyers in the area actively seek homes with pools, the appraiser may assign a higher value.
  • Maintenance & Safety: Older pools that require repairs or pose safety hazards might even result in a negative adjustment.

On average, appraisers often adjust for pools or spas in the range of $20,000–$50,000, depending on the factors above — though this can vary widely based on location and comparable sales.

4. Buyer Considerations

Not all buyers see pools as a benefit. Some may view them as high-maintenance features that increase water bills, chemical upkeep, and liability risks. This can influence how much an appraiser considers the pool in the final valuation.

5. Maximizing Pool Value

To make your pool a positive factor in your home’s appraisal:

  • Keep it clean and well-maintained
  • Ensure all equipment is functional
  • Highlight energy-efficient upgrades (solar heating, automated systems)
  • Document recent repairs or improvements

Final Thoughts

While pools and spas rarely recoup 100% of their installation costs, they can boost your home’s marketability and help your property stand out — especially in San Diego’s competitive market. For sellers, a clean, updated, and well-maintained pool often translates to higher buyer interest, faster sales, and potential appraisal adjustments.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News April 24, 2026

How Trees Affect Property Values: A Real Estate Perspective

How Trees Affect Property Values: A Real Estate Perspective

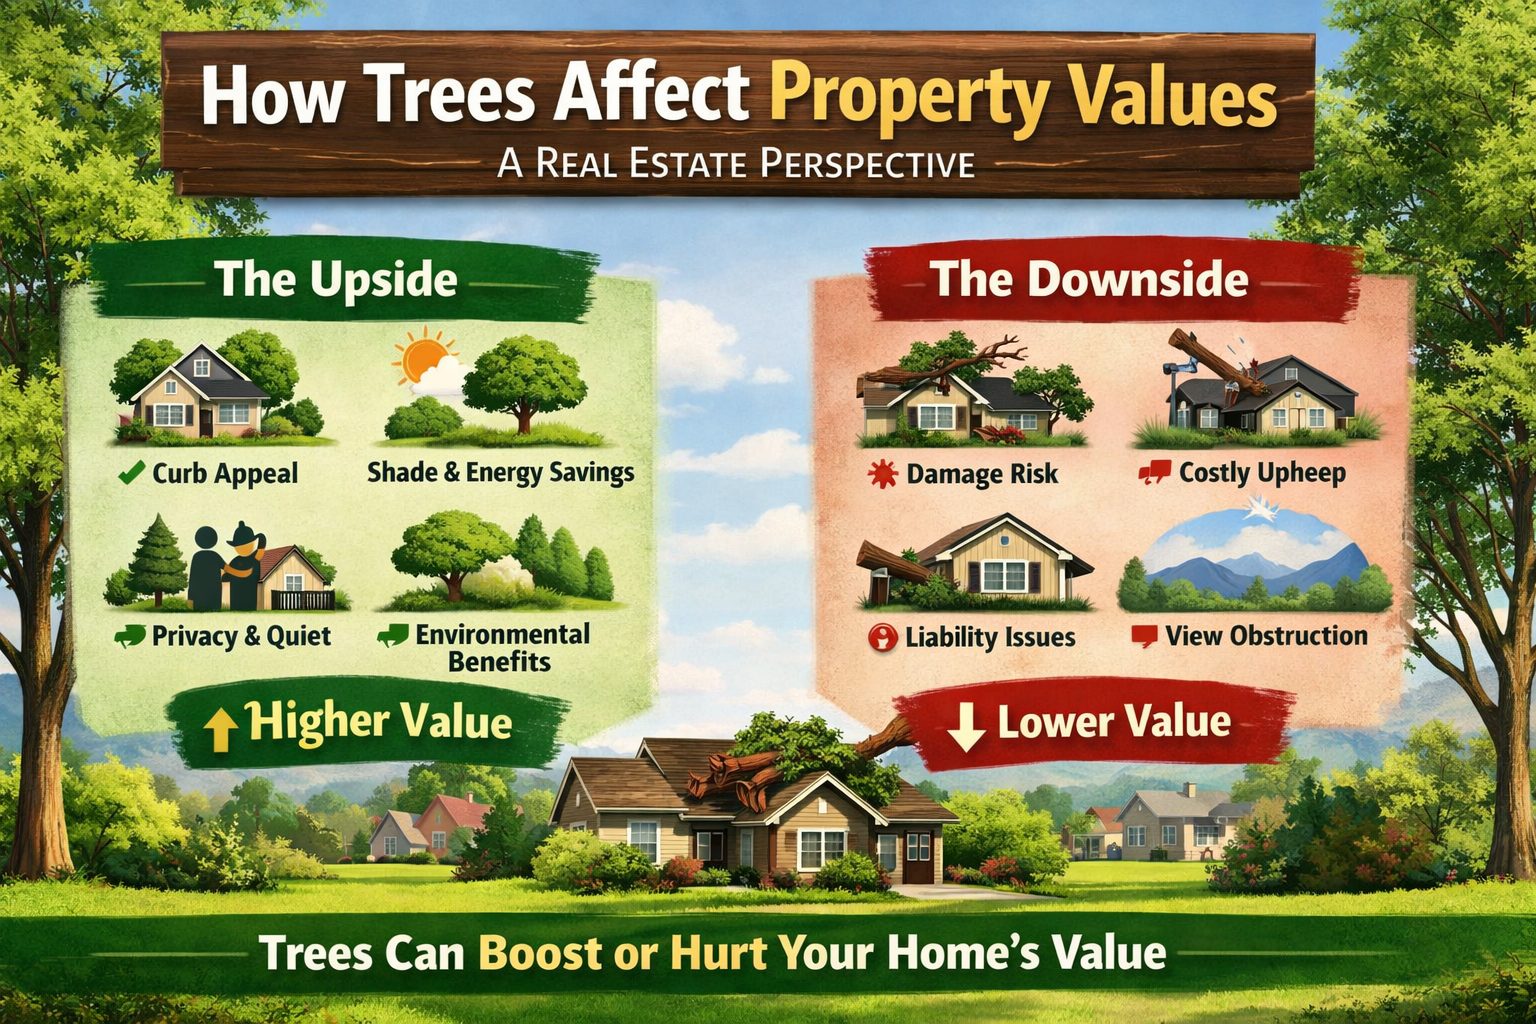
Trees do more than make a property look attractive — they can directly influence home value, marketability, and buyer perception. Depending on their type, location, and condition, trees can either boost a home’s value or create concerns that impact pricing and demand. Here’s how trees factor into real estate value.

How Trees Can Increase Property Value

1. Curb Appeal Mature, healthy trees add character and visual appeal. Homes with attractive landscaping often sell faster and can command higher prices because first impressions matter.

2. Shade and Energy Efficiency Strategically placed trees can reduce cooling costs by providing natural shade. In warmer climates, buyers often see this as a long-term cost-saving benefit.

3. Privacy and Noise Reduction Trees act as natural buffers from neighbors and streets, creating a sense of privacy that many buyers are willing to pay for.

4. Environmental and Lifestyle Appeal Trees improve air quality, support wildlife, and create inviting outdoor spaces — features increasingly valued by eco-conscious buyers.

5. Higher Appraised Value Well-maintained landscaping, including trees, can contribute to higher appraisals when it enhances overall property appeal and usability.

When Trees Can Hurt Property Value

6. Maintenance and Cost Concerns Large or aging trees require pruning, watering, and occasional removal. Buyers may factor these future expenses into their offers.

7. Risk to Structures Trees planted too close to the home can threaten foundations, roofs, plumbing lines, and sidewalks through invasive root systems.

8. Insurance and Liability Issues Dead or damaged trees may increase insurance premiums or raise liability concerns if branches pose a risk to neighboring properties.

9. Overgrown or Unmanaged Landscaping Neglected trees can make a property feel dark, crowded, or poorly maintained, turning buyers off rather than impressing them.

10. View Obstruction In areas where views are a major selling point, trees that block ocean, mountain, or city views can significantly reduce value.

What Buyers and Sellers Should Know

  • Healthy, well-placed trees generally add value
  • Poorly maintained or hazardous trees can lower offers
  • Location and species matter as much as size
  • Professional trimming before listing can improve marketability

Bottom Line

Trees are a powerful but often overlooked factor in real estate value. When properly maintained and thoughtfully positioned, they can enhance beauty, comfort, and resale value. When neglected or poorly placed, they can create costly challenges. For homeowners considering selling, a tree assessment may be just as important as staging or paint.

If you’re unsure whether your trees are helping or hurting your home’s value, a local real estate professional can provide guidance tailored to your market.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News April 15, 2026

The Tax Benefits of Owning a Home in San Diego County

The Tax Benefits of Owning a Home in San Diego County

Buying a home in San Diego County doesn’t just provide stability, a place to call your own and the chance to build equity—it also opens up a number of tax benefits you should know about. Of course, every homeowner’s situation is different so you’ll want to consult your tax professional. But here’s a broad, blog-style overview of the key tax advantages (and some of the limitations) of home ownership in California (and thus for San Diego County).


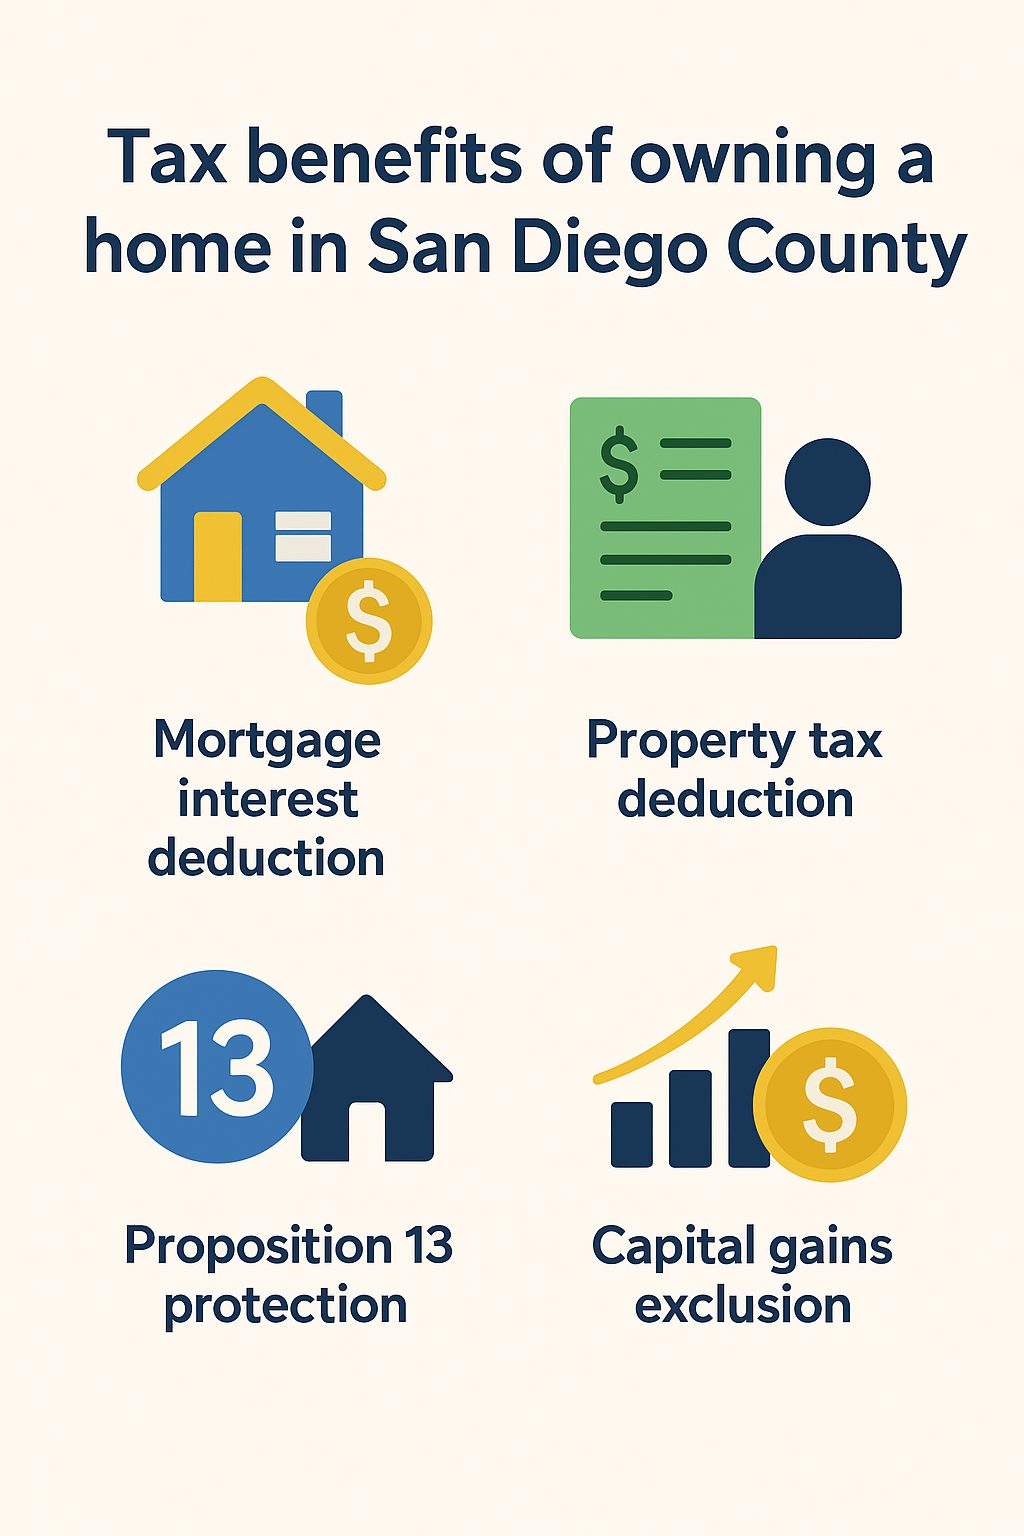
1. Mortgage Interest Deduction

One of the classic tax benefits of home-ownership is the ability to deduct the interest on your mortgage.

  • If you itemize your deductions on your federal tax return, you may deduct the interest you pay on a qualified home loan for your primary residence (and in many cases a second home).
  • Under current rules: For mortgages taken out after December 15, 2017, the deduction limit is on interest paid on up to $750,000 of mortgage debt for married couples filing jointly (or $375,000 if married filing separately). For mortgages taken out before that date, older rules (e.g., $1 million limit) may apply.
  • If you moved money around (for example a home-equity loan or line of credit), note: interest you pay may only be deductible if the borrowed funds were used to “buy, build or substantially improve” the home.

What this means for a San Diego homeowner:
If you buy a home, the interest component of your mortgage in early years is often relatively high (because amortization). Deducting this can reduce your taxable income, lowering your tax bill.

But a caveat:
You must itemize your deductions in order to claim mortgage interest. If your total itemized deductions are less than the standard deduction (see later), then the benefit may be minimal or non‐existent.


2. Property Tax Deduction & SALT Cap

Another major benefit: property taxes you pay are in many cases tax‐deductible. But there are also important limits to understand.

Property Tax Deduction

  • Homeowners in California can deduct property taxes (and certain other local taxes) on their federal returns, when they itemize.
  • In California, for example, there’s also a “homeowners’ exemption” that lowers the assessed value of your principal residence by $7,000 (which modestly reduces the property tax owed).

SALT (State and Local Tax) Deduction Cap

  • Under federal tax law (the Tax Cuts and Jobs Act of 2017 and subsequently), the deduction for state and local taxes (SALT) — which includes property tax, state income tax, and local sales tax — is capped at $10,000 (for married filing jointly) for tax years 2018 through 2025.
  • Accordingly: Even if you pay $12,000 (or $15,000) in property taxes in San Diego County, your deduction for federal purposes may be limited by that $10,000 cap (if your state income tax + property tax + sales tax combined exceed it).

What this means for a San Diego homeowner:
Since San Diego is a higher-cost area, property tax bills can be sizeable. The ability to deduct them is real, but the SALT cap often limits how much benefit you get at the federal level. At the state level (California), there is no SALT cap effect, so you may still deduct full property tax on your state tax return (depending on your circumstances) because California does not impose that same $10k cap for its own tax calculus.


3. Capital Gains Exclusion When You Sell

Owning your home gives you a powerful benefit when it’s time to sell: the capital gains tax exclusion.

  • Under federal law, if you’ve lived in your home as your primary residence for at least two of the last five years, you can exclude up to $250,000 of capital gain from your income if you are single, or up to $500,000 if married filing jointly.
  • This means: Suppose you buy a home in San Diego County, live in it for 2+ of the last 5 years, and sell it for a higher price—if your gain falls under those thresholds, you may owe no federal capital gains tax on that portion.
  • In California, your gain may still be subject to the state tax, but the federal exclusion is considerable.

Why this matters in San Diego:
With home prices and appreciation in many San Diego neighborhoods, the potential gain can be large. The exclusion gives you peace of mind that a large portion (or all) of the gain may avoid federal tax—with proper planning.


4. Homeowners’ Exemption & Proposition 13 Protections

In California, there are constitutional and statutory protections that benefit homeowners—not just tax deductions but structural advantages.

  • California Proposition 13 (1978) limits the property tax rate on real property to 1% of the assessed value (except for voter-approved local assessments) and restricts annual assessment increases of the taxable value of a property to a maximum of 2% per year, unless there is a change in ownership or new construction.
  • The “homeowners’ exemption” in California allows a reduction in assessed value of $7,000 for a qualified residence. (As noted above.)

Why this is beneficial:
Even though California property values (and thus taxes) may be high in San Diego County, these protections illustrate that tax burdens don’t rise uncontrollably. Your tax is limited to 1% of assessed value (plus voter‐approved amounts), and the assessed value only increases modestly each year (so long as you don’t sell or significantly alter the property). That stability is a meaningful advantage of home-ownership in California.


5. Energy-Efficient Improvement Credits & Home Office Deductions

Beyond the big ticket items, there are additional tax wins for homeowners who make certain investments.

  • If you install renewable energy systems (solar panels, battery storage) or make qualified energy-efficient home improvements, you may be eligible for federal tax credits (for example, the Residential Clean Energy Credit) or state incentives.
  • If you run a business from home (for example you’re self-employed or work remotely and qualify), you may be able to claim a home office deduction (in certain cases) which allocates a portion of mortgage interest, utilities, repairs and depreciation to that business area.

Relevance for San Diego homeowners:
Given California’s push toward renewable energy and San Diego’s generally favorable climate for solar, this is a meaningful added benefit. If you’re doing business from home or using part of the home exclusively and regularly for business, those deductions may apply.


6. Putting It All Together: What A Homeowner in San Diego Should Know

Here are some practical considerations and pitfalls.

✅ Advantages

  • You get to deduct mortgage interest (if you itemize) — that can be one of the largest deductions in early years.
  • You can deduct property taxes at the federal level (within limits) and fully (typically) at the California state level.
  • You benefit from the capital gains exclusion when you sell your primary residence (assuming you meet conditions).
  • California’s Proposition 13 and the homeowners’ exemption give structural tax stability and protection.
  • Additional credits or deductions for energy improvements or certain home uses may further benefit you.

⚠️ Limitations / Things to Watch

  • To get most of these benefits, you must itemize your deductions. If your itemized deductions (mortgage interest + property tax + other deductible expenses) don’t exceed the standard deduction, it may not “pay” for its complexity. For example: Some homeowners discover they still take the standard deduction because it’s larger.
  • The SALT deduction cap (state and local taxes limitation) means that in high tax states like California, the benefit of property tax deduction is limited on the federal side: you can deduct only up to $10,000 (for the combined state income + property + sales taxes) for many taxpayers.
  • The mortgage interest deduction limit ($750k) means if you purchase a very expensive home with a large loan, a portion of the interest might not be deductible under the newer rules.
  • Deductions change year to year—as do tax laws—so staying updated is critical.

💡 Tips for San Diego Homeowners

  • Keep accurate records: mortgage interest statements (Form 1098), property tax bills, receipts for any home improvements, and documentation if you use a home office.
  • Early in home-ownership, run projections: How much interest will I pay in year 1? How high are my property taxes (San Diego County has higher home values, and thus higher taxes). Will I exceed the standard deduction when adding everything up?
  • Consider state vs federal implications: On the California return, you may have different deduction rules than federally.
  • When you sell or refinance, consult tax advice: Because of the capital gains exclusion and potential recapture or reassessment triggers in California, planning ahead helps.
  • For energy upgrades: If you’re in San Diego and installing e.g. solar panels, you may reduce your utility bills and claim credits — a double win.

Conclusion

Owning a home in San Diego County brings more than just the emotional and lifestyle benefits—it offers tangible tax advantages, including interest deductions, property tax deductions (within limits), capital‐gain exclusions, structural tax protections via Proposition 13, and potential credits/deductions for energy improvements or business use.

That being said: Buying a home primarily for tax savings isn’t usually wise. The tax benefits help, but they typically don’t overwhelm the costs of home-ownership (maintenance, insurance, property tax, mortgage rates, etc.). Instead think of them as one of several factors in the overall decision.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News April 1, 2026

What Makes a Community Walkable? A Homebuyer’s Guide

What Makes a Community Walkable? A Homebuyer’s Guide

When buyers talk about wanting a “walkable neighborhood,” they’re often envisioning more than just sidewalks and streetlights. Walkability is about convenience, lifestyle, health, and community connection—all rolled into one. Whether you’re shopping for a home in North San Diego County or simply curious about what truly defines a walkable community, here are the key features to look for.


1. Convenient Access to Everyday Essentials

A walkable community places your daily needs within a short stroll.
This includes:

  • Grocery stores
  • Coffee shops
  • Restaurants
  • Pharmacies
  • Local services (dry cleaning, barber, fitness studios)

The idea is simple: fewer car trips, more fresh air.


2. Safe and Connected Infrastructure

Walkability starts with thoughtful design. Look for:

  • Wide, well-maintained sidewalks
  • Pedestrian-friendly street crossings
  • Traffic-calming features like speed bumps and roundabouts
  • Adequate lighting for evening walks

These elements create a safe, comfortable path for residents of all ages.


3. Proximity to Parks and Recreation

Whether it’s a quiet neighborhood park, dog park, hiking trail, or a community center, recreational spaces encourage people to walk more often. In San Diego County, this often means access to coastal trails, canyon routes, and large public parks that make walking not just practical, but enjoyable.


4. A Mix of Housing and Land Use

Walkable communities often offer a blend of:

  • Single-family homes
  • Townhomes
  • Condos
  • Mixed-use buildings

When shops, residences, and businesses are woven together, the neighborhood becomes more vibrant and accessible.


5. Public Transportation Options

Even if you prefer walking, it helps to live near reliable transit. A walkable area typically provides easy access to:

  • Bus stops
  • Rapid transit lines
  • Trolley stations (in areas like downtown, La Mesa, and UTC)

This connectivity reduces dependence on cars and adds flexibility to your daily routine.


6. Inviting Streetscapes and Community Spaces

Walkability isn’t only about distance—it’s also about enjoyment. The best walkable communities include:

  • Shade trees
  • Benches and seating areas
  • Public art
  • Clean, welcoming storefronts

These features encourage people to linger, socialize, and explore.


7. A Strong Sense of Community

Walkable areas naturally bring neighbors together. When people see each other regularly—at the local café, market, or on evening walks—it strengthens community ties and enhances quality of life.


Why Walkability Matters in Real Estate

Homes in walkable neighborhoods often enjoy:

  • Higher property values
  • Better long-term demand
  • Lower transportation costs
  • Healthier lifestyles

For buyers in San Diego County, a walkable community can be a major advantage—especially as traffic concerns and gas costs continue to rise.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News March 29, 2026

How Long Does It Really Take to Purchase a House?

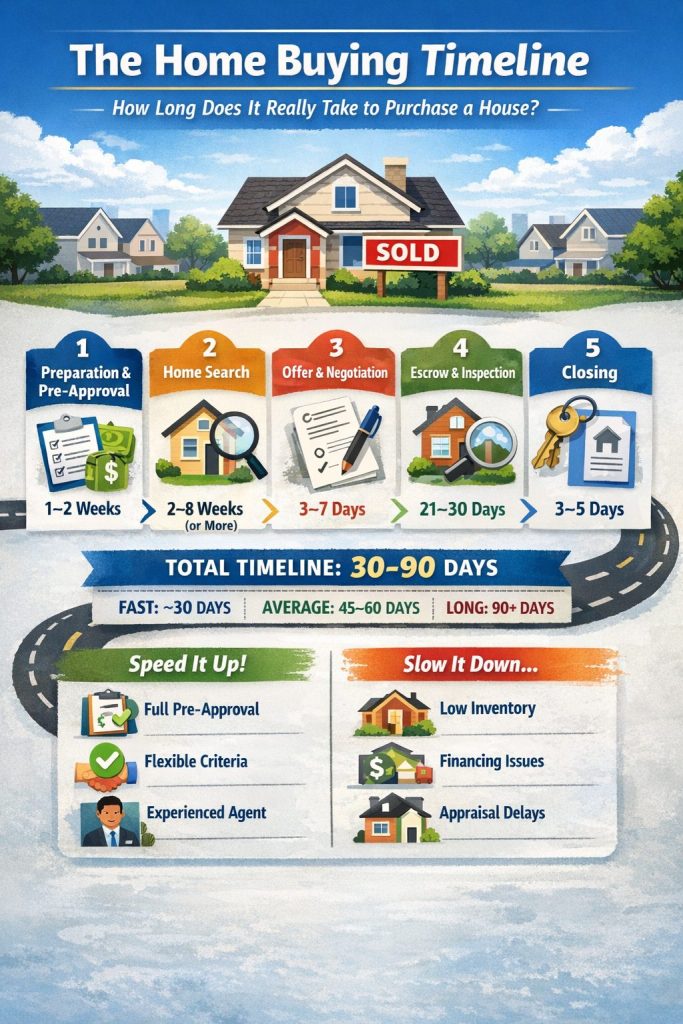
🏡 The Home Buying Timeline: How Long Does It Really Take to Purchase a House?

Buying a home is one of the biggest financial decisions you’ll make—and one of the most common questions is: “How long does the process actually take?” The answer depends on your preparation, the market, and financing—but here’s a clear, realistic timeline to guide your expectations.


🔍 Step 1: Preparation & Pre-Approval (1–2 Weeks)

Before you even start house hunting, you’ll want to get your finances in order.

What happens here:

  • Review credit, income, and debt
  • Meet with a lender
  • Get pre-approved for a mortgage

Why it matters:
Pre-approval strengthens your offer and helps you understand your true budget—critical in competitive markets like San Diego County.


🏠 Step 2: Home Search (2–8 Weeks or More)

This is often the most unpredictable part of the process.

What affects timing:

  • Inventory levels
  • Your price range
  • How specific your needs are
  • Market competition

Pro tip:
In a fast-moving market, buyers may find a home in days. In slower markets, it could take months.


✍️ Step 3: Making an Offer & Negotiation (3–7 Days)

Once you find the right home, things move quickly.

This stage includes:

  • Submitting an offer
  • Negotiating price and terms
  • Seller acceptance

In competitive situations, decisions can happen within hours.


🔎 Step 4: Escrow & Due Diligence (21–30 Days)

This is the most structured phase of the transaction.

Key milestones:

  • Home inspection (within first 7–10 days)
  • Appraisal ordered by lender
  • Loan underwriting
  • Contingency removals

This period ensures the home and financing meet all requirements before closing.


🔑 Step 5: Closing (3–5 Days)

You’re almost there!

Final steps:

  • Signing loan documents
  • Final walkthrough
  • Recording the sale
  • Getting the keys

⏱️ Total Timeline: 30–90 Days (Typical)

  • Fast scenario: ~30 days (cash buyer or quick decision-making)
  • Average: 45–60 days
  • Longer timeline: 90+ days (extended home search or financing delays)

📍 What Can Speed Things Up?

  • Full loan pre-approval (not just pre-qualification)
  • Flexible home criteria
  • Working with an experienced local agent
  • Strong, clean offers

⚠️ What Can Slow Things Down?

  • Low inventory
  • Financing complications
  • Appraisal issues
  • Extensive negotiations or repairs

🏁 Final Thoughts

While the home buying process can feel complex, understanding the timeline helps you stay confident and in control. Whether you’re buying your first home or your next investment, preparation and the right team can make all the difference.

If you’re considering buying in North San Diego County, knowing these timelines can help you plan strategically and compete effectively in today’s market.


Thinking about making a move? Now is the time to start the conversation and map out your personalized home buying timeline. Start searching for free!


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News March 25, 2026

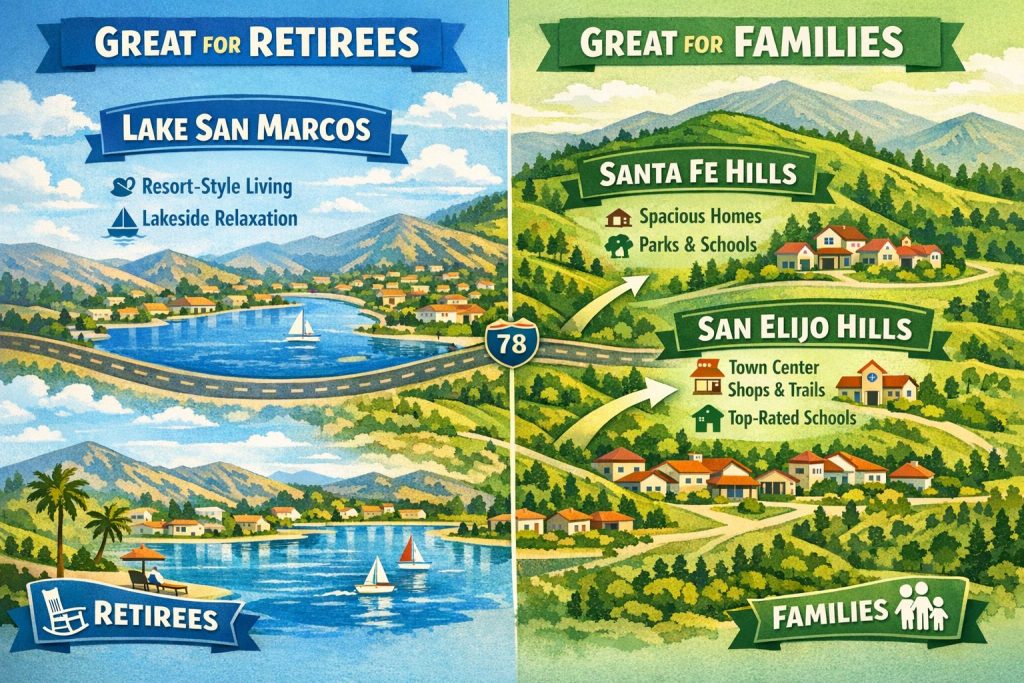
Lake San Marcos vs Santa Fe Hills vs San Elijo Hills

Lake San Marcos vs Santa Fe Hills vs San Elijo Hills


1. Lake San Marcos

Location & Community:

  • Nestled around a private, scenic lake in San Marcos, offering a small-town, resort-like feel.
  • Popular with retirees and those seeking a slower pace of life; active 55+ communities are prevalent.

Lifestyle & Amenities:

  • Walking trails around the lake, fishing, boating, and a golf course.
  • Many social clubs, community centers, and senior-focused activities.
  • Quiet and serene, less traffic and fewer crowds.

Housing:

  • Mix of single-family homes, condos, and villas.
  • Homes often have lake or golf course views.
  • Generally higher age-restricted communities with moderate to higher price points.

Pros:

  • Scenic and tranquil, resort-style amenities.
  • Tight-knit, slower-paced community.

Cons:

  • Less ideal for young families; fewer schools nearby.
  • Some areas may feel isolated from shopping and urban conveniences.

2. Santa Fe Hills

Location & Community:

  • Part of North San Marcos, newer master-planned neighborhoods.
  • Designed for families and professionals; suburban feel.

Lifestyle & Amenities:

  • Modern parks, trails, and green belts.
  • Community events geared towards families and children.
  • Good access to shopping and freeway connections.

Housing:

  • Larger, modern single-family homes.
  • Higher elevation means some homes have valley or hillside views.
  • Price points tend to be higher due to newer construction and lot sizes.

Pros:

  • Family-friendly, safe, and modern.
  • Quick access to amenities and schools.

Cons:

  • Less “resort” feel; more suburban and structured.
  • Can feel less scenic compared to Lake San Marcos.

3. San Elijo Hills

Location & Community:

  • Located in the coastal hills of San Marcos; highly planned community.
  • Designed for families, but has a mix of ages and lifestyles.

Lifestyle & Amenities:

  • Town-center concept with shops, restaurants, and cafes.
  • Walking trails, parks, and community events (farmers’ markets, concerts).
  • Schools are highly rated; strong focus on family life.

Housing:

  • Mix of single-family homes and some townhomes.
  • Homes are often architecturally appealing, with some hillside views.
  • Price point is comparable to Santa Fe Hills but can vary based on lot and view.

Pros:

  • Walkable town-center lifestyle.
  • Family-oriented, strong school district.
  • Beautiful, maintained landscaping and hillside views.

Cons:

  • Slightly higher density than Santa Fe Hills or Lake San Marcos.
  • Less privacy in some neighborhoods.

Summary Table

Feature Lake San Marcos Santa Fe Hills San Elijo Hills
Best For Retirees, quiet lifestyle Families, professionals Families, active lifestyle
Housing Type Condos, villas, single-family Modern single-family Single-family, some townhomes
Community Feel Resort-like, relaxed Suburban, safe Walkable, family-friendly
Amenities Lake, golf, walking trails, social clubs Parks, trails, modern amenities Parks, trails, town center, shops
School Access Limited Good Excellent
View / Scenery Lake & golf views Hills & valley views Hillside views, landscaped
Price Range Moderate-high High High

Key Takeaways:

  • Lake San Marcos is ideal for tranquility and scenic, lake-focused living—more for retirees than young families.
  • Santa Fe Hills is modern and family-focused, with larger homes and good suburban amenities.
  • San Elijo Hills blends family living with a walkable town-center feel and strong schools, plus some scenic hillside views.

Are you thinking of moving to San marcos, CA? Contact me, Steve Cardinalli, for a list of homes in your budget or start your search here: San Marcos, CA.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News March 21, 2026

Do I Have to Disclose If My Home Is in a Flood Zone When Selling It?

Do I Have to Disclose If My Home Is in a Flood Zone When Selling It?

When selling a home, transparency isn’t just good practice—it’s the law. One of the most common questions sellers ask is whether they’re required to disclose if their property is located in a flood zone. The short answer? Yes. In California (and most states), sellers must disclose this information to potential buyers as part of the natural hazard disclosure process.

Understanding Flood Zone Disclosures

A flood zone is an area that has a certain level of risk for flooding as determined by the Federal Emergency Management Agency (FEMA). Flood maps categorize areas based on their likelihood of flooding—ranging from minimal risk to high-risk floodplains that require mandatory flood insurance for federally backed mortgages.

If your property lies within one of these zones, that information must be shared with buyers before closing.

California’s Natural Hazard Disclosure (NHD) Report

In California, state law (Civil Code §1103) requires sellers to provide buyers with a Natural Hazard Disclosure (NHD) Report. This document, typically prepared by a third-party company, informs buyers if the property is located in any of six state-mapped hazard zones, including:

  • A Special Flood Hazard Area (FEMA flood zone)
  • A Very High Fire Hazard Severity Zone
  • A Wildland Fire Area
  • An Earthquake Fault Zone
  • A Seismic Hazard Zone (liquefaction or landslide risk)
  • A State Responsibility Area for wildfires

Failing to provide this disclosure can expose sellers to legal liability, including potential lawsuits for nondisclosure.

Why Flood Zone Disclosures Matter

Disclosing a flood zone isn’t just about following the law—it’s about protecting both buyer and seller.

  • For buyers: It allows them to plan for flood insurance and understand potential risks.
  • For sellers: It demonstrates honesty and reduces the risk of future disputes or claims of misrepresentation.

Buyers are far more likely to trust a seller who is transparent from the beginning.

What If You’re Unsure?

If you’re not sure whether your property is in a flood zone, your real estate agent or NHD provider can help obtain a reliable report. You can also check FEMA’s Flood Map Service Center online for a free map of your property’s risk area.

Bottom Line

Yes, you must disclose if your home is in a flood zone when selling it in California. Providing a complete Natural Hazard Disclosure report ensures compliance with the law and helps build trust with your buyers. It’s a small step that can prevent big problems down the road.


Be the first to know about the market trend in your community at Neighborhood News


Real Estate News March 18, 2026

San Diego County Real Estate Market Insights — March 2026

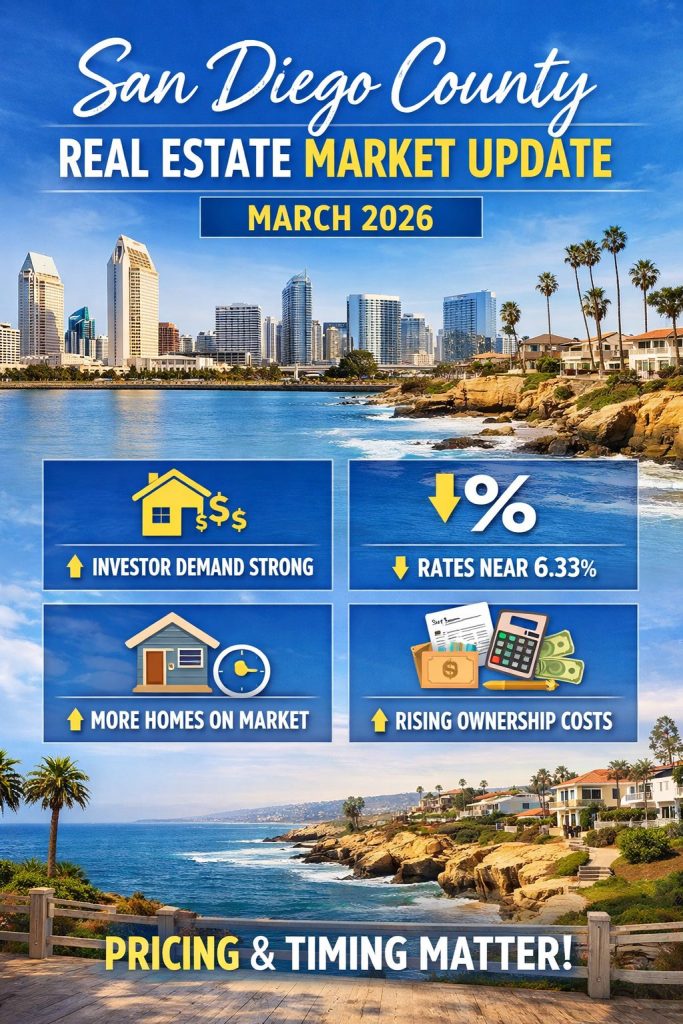
🏡 San Diego County Real Estate Market Insights — March 2026

📈 Spring Market Gaining Traction — But Still Competitive

The San Diego housing market continues its slow, steady evolution as we settle into the spring buying season. Local data and recent market signals show:

  • Investor demand remains significant in major California markets, including San Diego, as investors expand activity even amid affordability challenges.
  • Mortgage rates nationally have dipped slightly, with the 30‑year average recently at ~6.33%.
  • This rate environment — while higher than the ultra‑low pandemic years — is encouraging some sidelined buyers back into the market.

For San Diego specifically, buyer interest is rebounding after winter, but affordability and inventory levels still shape the pace of activity.


📊 Local Inventory & Price Dynamics

San Diego’s housing inventory and pricing reflect a nuanced marketplace:

  • Inventory remains below balanced levels, showing more options than in recent peaks but still under the traditional “six‑month supply” that indicates equilibrium.
  • Some neighborhoods may see increased for‑sale activity, especially as sellers target peak viewing weeks in spring. Historically, listings mid‑April tend to sell faster and often for more.
  • Luxury home inventory growth has pushed the market time for high‑end properties (above $2 M) upward, meaning slower sales in that segment compared with lower‑priced tiers.

💡 What this means for your clients: The market isn’t “stuck,” but pricing and timing are key — especially for sellers in higher price brackets and buyers trying to balance cost with value.


🔍 Buyer Trends You’re Seeing Locally

Many San Diego buyers and agents are reflecting a few key realities in 2026:

📍 Affordability Challenges Still Loom

Even though mortgage costs softened slightly in recent months, buyers in San Diego still struggle with high home prices relative to local wages — with median prices above $1 M in many parts of the county.

📍 More Properties Are Staying on Market Longer

With increased listings compared to a year ago, homes that aren’t competitively priced are staying on the market longer, particularly outside the most desirable price points and neighborhoods.

📍 Buyers Are More Disciplined

Agents report that today’s buyers are:

  • More cautious about overbidding
  • Focused on properties priced correctly
  • Monitoring total ownership costs — including taxes, HOA fees, and insurance, not just mortgage payments

These behaviors reflect broader national trends around hidden housing costs rising faster than wages, squeezing affordability.


📈 What This Means for Sellers

Here’s how you might position your listings right now:

  • Price with precision: Overpricing can lengthen days on market and push buyers toward other options.
  • Capitalize on spring demand: Traditionally, mid‑April through May attracts more buyers and faster sales.
  • Highlight value: Features like remodeled kitchens, outdoor living spaces, and energy‑efficient upgrades resonate with buyers balancing costs and lifestyle.

📉 What This Means for Buyers

For buyers in San Diego County:

  • Don’t wait for huge price drops: Local data hasn’t shown any major price collapses — only modest shifts and neighborhood variability.
  • Get financing ready today: Even small declines in mortgage rates can improve affordability.
  • Think long game: Buying in strong markets like San Diego often rewards patience and strategic negotiation.

📣 Final Takeaways

San Diego County’s housing market in March 2026 is balanced between opportunity and challenge:

✔ Inventory is slowly increasing but still modest compared to long‑term norms.
✔ Mortgage rates are stabilizing near 6%, giving some buyers confidence to act.
✔ Buyers are disciplined, and sellers must price strategically to capture attention.
✔ Hidden ownership costs — taxes, insurance, HOA — are climbing nationwide and matter locally too.

Bottom line: Contact me, Steve Cardinalli, if you’re listing a property this spring, timing and pricing precision will be your edge. And for buyers, readiness and realistic budgeting are key to securing a home in this still‑competitive San Diego market.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News March 6, 2026

Has the War in the Middle East Impacted the Real Estate Market in San Diego County?

Has the War in the Middle East Impacted the Real Estate Market in San Diego County?

Global events often dominate the headlines, but many homebuyers and sellers wonder whether international conflicts—like the current war in the Middle East—actually affect the local real estate market in San Diego County. The short answer is: yes, but mostly indirectly. While wars rarely change home values overnight, they can influence economic factors that shape housing demand, mortgage rates, and buyer confidence.

The Direct Impact on Home Prices Is Usually Limited

Real estate markets are primarily driven by local supply and demand—things like population growth, housing inventory, and local job markets. Historically, international conflicts alone do not immediately change home values in a specific city or county.

In San Diego County, factors such as limited housing supply, strong job sectors, and desirable coastal living typically play a much larger role in determining property values than events overseas.

However, global conflicts can influence several economic factors that eventually ripple into the housing market.


1. Mortgage Rates Can Move Because of Global Instability

One of the most immediate ways war can affect real estate is through mortgage rates. Rates are tied closely to bond markets and inflation expectations.

Recent economic reports show that the conflict involving Iran has pushed bond yields higher and nudged the average U.S. 30-year mortgage rate back to around 6% after briefly dipping below that level.

Mortgage rates fluctuate during geopolitical crises because investors shift money into safer assets like U.S. Treasury bonds. These shifts can either lower or raise borrowing costs depending on inflation expectations and oil prices.

For San Diego buyers, even a small rate change can significantly impact purchasing power in an already expensive market.


2. Oil Prices and Inflation Affect Housing Costs

The Middle East plays a critical role in global oil supply. When conflict threatens shipping routes like the Strait of Hormuz, energy prices often spike.

Higher oil prices can lead to:

  • Increased inflation
  • Higher construction and transportation costs
  • Rising interest rates

Economists warn that energy price spikes from the conflict are already pushing oil above $80 per barrel and raising inflation concerns globally.

If inflation stays elevated, the Federal Reserve may keep interest rates higher for longer, which could slow buyer demand in expensive housing markets like San Diego.


3. Economic Uncertainty Can Affect Buyer Confidence

Another indirect effect is psychology. When global tensions rise:

  • Stock markets may become volatile
  • Consumer confidence can decline
  • Buyers may pause major financial decisions

For example, financial markets recently dropped sharply amid fears that the conflict could disrupt oil supplies and economic growth.

When buyers feel uncertain about the economy, they may delay purchasing homes, which can temporarily slow housing activity.


4. Why San Diego May Be More Resilient

Despite global uncertainty, San Diego County often remains resilient because of several unique factors:

  • Limited land for new construction
  • Strong military and defense employment
  • High demand for coastal housing
  • Continued population growth

These fundamentals help stabilize home values even when national or global events create short-term economic turbulence.


The Bottom Line

The war in the Middle East is unlikely to directly change home prices in San Diego County overnight. However, it can influence the housing market indirectly through:

  • Mortgage rate fluctuations
  • Inflation and energy prices
  • Consumer confidence and economic uncertainty

For buyers and sellers, the key takeaway is that local fundamentals still matter most. While global events may cause temporary shifts in interest rates or market sentiment, San Diego’s housing market continues to be driven primarily by its strong demand and limited supply.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News

Real Estate News February 28, 2026

How the U.S.–Iran Conflict May Influence U.S. Real Estate Prices in 2026

How the U.S.–Iran Conflict May Influence U.S. Real Estate Prices in 2026

Geopolitical events rarely occur in an economic vacuum — and the ongoing U.S. and allied military action against Iran has already sent ripples across global markets and investor sentiment. On February 28, 2026, U.S. and Israeli forces launched strikes targeting Iran’s leadership and military infrastructure, and Iran has retaliated with missile launches across the region. The situation has escalated to a broader Middle East confrontation with implications for global oil prices, economic confidence, and financial markets.

So what does this mean for U.S. real estate prices?


📈 1. Mortgage Rates & Borrowing Costs Could Rise

One of the most direct ways geopolitical upheaval affects real estate is through interest rates:

  • Tensions tend to spike oil prices, which can fuel inflation. Higher inflation often leads the Federal Reserve to maintain or raise interest rates to dampen price increases.
  • Higher rates translate into higher mortgage costs, reducing buyer affordability — especially at the entry-level or for first-time buyers.

Bottom line: If inflationary pressures persist, expect mortgage rates to stay elevated longer, which could cool price growth in some housing markets.


📉 2. Investor Sentiment & Capital Flows Shift

When major conflicts break out, markets become risk-averse:

  • Investors often flee to “safe havens” like gold and government bonds, and away from higher-risk assets like commercial real estate or speculative housing investments.
  • Global uncertainty can slow foreign investment into U.S. property — a segment that has helped sustain prices in gateway cities.

This hesitation can dampen speculative demand, especially in luxury and commercial sectors.


🛢️ 3. Energy Markets & Consumer Budgets Impact

Iran plays a strategic role in global oil flow, including through the Strait of Hormuz. Any conflict that risks disrupting exports could lead to higher energy prices — which have a cascading impact:

  • Higher gasoline and heating costs squeeze household budgets.
  • More of a buyer’s monthly income goes to essentials, reducing what they can afford for housing.

For real estate professionals, this means affordability metrics — already tight in many regions — could get even tighter if energy prices surge.


🧨 4. Regional Differences in Real Estate Demand

Not all markets react the same during uncertainty:

Resilient Markets

  • Stable, high-demand areas with strong job markets (e.g., tech hubs, Sun Belt cities).
  • Multifamily and rental markets that benefit from scarcity of homeownership affordability.

⚠️ More Vulnerable Markets

  • High-end luxury segments where investor demand is a bigger price driver.
  • Hospitality and retail real estate, which are more sensitive to economic slowdowns.

Put simply: core residential markets may withstand pressure better than riskier commercial sectors.


🏠 5. What U.S. Buyers & Sellers Should Watch

Here are proactive insights for your audience:

📍 Buyers:

  • Lock in today’s rates if affordability is a concern — don’t assume rates will fall quickly just because of uncertainty.
  • Focus on fundamentals: job growth, local demand, and population trends matter more than global headlines.

📍 Sellers:

  • Price homes competitively — fear can keep buyers on the sidelines.
  • Highlight value drivers like low local inventory, school districts, and walkability.

📍 Investors:

  • Diversify portfolios; consider stable cash-flow assets like multifamily or logistics properties.
  • Be cautious with highly leveraged purchases until volatility subsides.

🧠 Putting It All Together

While wars and geopolitical tensions can rattle markets, the U.S. housing market isn’t likely to “crash” solely because of the attack on Iran. Real estate is deeply tied to domestic fundamentals — employment, wages, lending standards — which remain strong in many parts of the U.S.

However, short-term volatility, higher mortgage rates, and investor caution are realistic scenarios that could slow price growth or shift demand between segments.

For real estate pros and consumers alike, the key is differentiating emotion from economics: global uncertainty influences confidence and money flows, but local market dynamics ultimately set prices.


Steve Cardinalli
Real Estate Professional, 01323509
(760) 814-0248
Steve@Cardinalli.com
www.Cardinalli.com
Century 21 Affiliated Fine Homes & Estates
Village Faire in Carlsbad Village
300 Carlsbad Village Dr, 223
Carlsbad, CA 92008


Be the first to know about the market trend in your community at Neighborhood News